A financial emergency can make speed feel like the only thing that matters. Medical expenses, essential repairs, education costs, or an unexpected payment may require funds before your regular cash flow can cover them. An urgent personal loan can provide access to unsecured funds, but speed should not come at the cost of ignoring interest, fees or repayment capacity.
Before applying, understand the expected disbursal timeline, total borrowing cost and whether the EMI fits your monthly budget.
When can an urgent Personal Loan help?
A Personal Loan can be used for any personal financial needs because it comes without any usage related restrictions. it may help with:
- Medical or emergency expenses
- Urgent home repairs
- Education-related payments
- Essential family expenses
- Consolidating costly outstanding debt
Borrowing should be based on repayment capacity, not simply on how quickly an application can be approved.
What should you check before applying?
When you need money urgently, compare the complete loan offer rather than focusing only on disbursal time.
Check:
- Interest rate: A lower interest rate can reduce EMI and total interest.
- Processing fee: Include applicable fees in the total cost. Check for low processing fee loans.
- Tenure: Choose a period that keeps the EMI manageable.
- Eligibility: Check income, credit profile and other criteria.
- Documentation: Know the required documents to avoid delays.
- Disbursal conditions: Approval and actual credit are separate steps.
How can an EMI Calculator help?
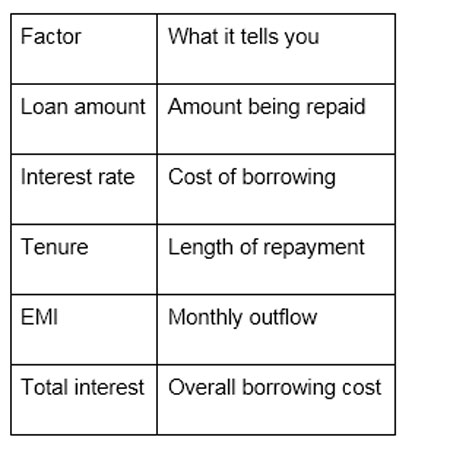
An EMI Calculator can show the expected monthly repayment before you submit an application. Enter the loan amount, interest rate and tenure to estimate the EMI.
Use it to compare scenarios rather than simply checking whether one EMI fits your budget. A lower interest rate can reduce the repayment burden, while a longer tenure can lower the monthly EMI but increase total interest.
Can an urgent Personal Loan be obtained quickly?
The process can be faster when an application is digital, and eligibility and documents can be verified promptly. However, do not assume every Personal Loan will be disbursed instantly. Timelines depend on the lender, verification and approval.
Keeping PAN, identity and income-related documents ready, where required, can help avoid delays. Review the Key Facts Statement and loan agreement before accepting the offer.
How does IDFC FIRST Bank fit into emergency borrowing?
For eligible customers, IDFC FIRST Bank’s FIRSTmoney Personal Loan offers a digital application journey with Video KYC and online processing. FIRSTmoney personal loans offer up to ?15 lakh, subject to eligibility, with flexible tenures and zero foreclosure charges.
This can be relevant when speed and digital processing matter, but borrowers should still check the applicable rate, processing fee, eligibility and expected disbursal timeline.
How should you use an EMI Calculator during an emergency?
Use the EMI Calculator before accepting an offer. Enter the loan amount, interest rate and tenure, then review the estimated EMI and total interest.
Next, compare the EMI with your monthly income and existing obligations. An EMI that fits technically may still leave too little for essential expenses.
Borrow only what you genuinely need and ensure repayment does not create another financial emergency.
Conclusion
An urgent personal loan can provide support when an unexpected expense cannot wait. However, speed should not replace careful comparison. Check the interest rate, fees, eligibility, repayment terms and disbursal conditions, and use an EMI Calculator to understand the monthly commitment before accepting the loan. The fastest loan is useful only when its repayment remains manageable.
FAQs
1. What is an urgent personal loan?
It is a personal loan sought when funds are needed quickly for an unexpected or time-sensitive requirement.
2. How quickly can a personal loan be disbursed?
The timeline varies by lender and depends on eligibility, verification, approval and documentation.
3. Can I use an EMI calculator before applying?
Yes. It can help estimate monthly repayment and compare interest-rate scenarios.
4. Does a quick loan mean a higher interest rate?
Not necessarily. Speed depends on the application process, while the rate depends on lender pricing and your profile.
5. Should I borrow the maximum amount offered?
No. Borrow based on your actual requirement and repayment capacity.