Daijiworld Media Network - New Delhi
New Delhi, Oct 8: Starting October 15, certain person-to-merchant (P2M) UPI transactions above Rs 2,000 will attract a Merchant Discount Rate (MDR) of 0.4%, with the charge capped at Rs 300 for transactions of Rs 75,000 or more.
However, railways, telecom services, insurance, fuel and certain utility-related payments will be subject to a flat MDR of Rs 5 per transaction, irrespective of the transaction value.
The Ministry of Finance said the flat-rate model is intended to prevent payment costs from escalating for critical public services, utility bill collection and thin-margin sectors such as fuel retail, while keeping essential services digitally efficient.
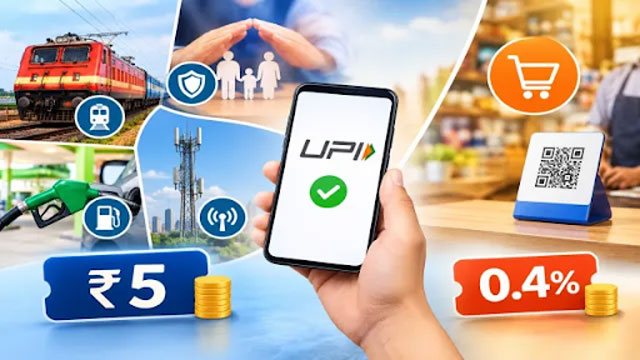
The differential structure has raised questions over why certain sectors receive a fixed cap while other eligible merchants face a percentage-based charge.
According to experts quoted by The Financial Express, the distinction reflects an attempt to balance the financial sustainability of the UPI ecosystem with the need to prevent disproportionate payment-acceptance costs for essential and relatively low-margin services.
Railways, fuel, telecom and insurance typically handle high transaction volumes and, in some cases, operate under regulated pricing or relatively narrow margins. Applying 0.4% across the board could therefore result in significantly higher payment costs without a corresponding increase in the underlying cost of processing a transaction.
The Rs 5 flat charge effectively provides sector-specific cost protection while ensuring that these transactions continue to contribute towards payment infrastructure.
For other eligible merchant transactions above Rs 2,000, the 0.4% MDR provides a value-linked contribution towards banking infrastructure, technology, cybersecurity and payment processing.
Ramkumar Subramanian, partner at Grant Thornton Bharat, told The Financial Express that the lower fixed cap for sectors such as railways, insurance, fuel and telecom is aimed at preserving affordability and encouraging digital payments in services with significant public-interest and inclusion dimensions. He said the differentiated structure seeks to balance consumer convenience, merchant economics and the long-term resilience of the digital payments ecosystem.
The cost difference becomes particularly clear with larger transactions. At Rs 2,000, a 0.4% MDR would amount to Rs 8, compared with Rs 5 under the concessional structure. The breakeven point is Rs 1,250, where 0.4% equals Rs 5.
Since the new MDR applies only to eligible transactions above Rs 2,000, the flat Rs 5 charge is effectively more favourable throughout the chargeable range. On a Rs 10,000 transaction, for instance, the standard MDR would be Rs 40, while a merchant in a concessional category would pay only Rs 5.
Prabhat Ranjan, senior director at Nexdigm said that the Rs 5 cap could significantly contain payment-acceptance costs for high-volume sectors, particularly as transaction values rise. However, he noted that the commercial impact would also depend on how revenue is distributed among acquiring banks, payment aggregators, payment service providers and other participants.
Ranjan also cautioned that attempts to recover the economics through differently labelled charges would need to comply with the regulatory framework. He stressed the importance of transparency in contractual arrangements across the payments ecosystem.
The differentiated MDR could also create a risk of merchant-category arbitrage or misclassification. Experts told The Financial Express that strong merchant onboarding, periodic validation of Merchant Category Codes and monitoring of transaction patterns would be necessary to prevent businesses from incorrectly seeking lower-cost categories.
Ranjan suggested maintaining clear audit trails for category changes, holding acquiring institutions accountable for incorrect classifications and using technology-led monitoring alongside proportionate penalties for deliberate misrepresentation. Subramanian similarly stressed data analytics, periodic audits and strict enforcement.
The question of who ultimately bears the MDR is also significant. While MDR is formally a merchant-side charge and is not payable by consumers, businesses may eventually factor their higher payment costs into their broader pricing decisions.
Ranjan said that highly competitive businesses may absorb most of the cost, while merchants with greater pricing flexibility could indirectly reflect part of it in general prices. Banks, payment apps and payment service providers could also absorb or redistribute some of the economics depending on their commercial arrangements.
Subramanian said the consumer impact may initially be limited as businesses and payment providers absorb much of the cost. Over time, however, merchants could respond through reduced discounts, lower loyalty benefits, convenience charges or marginal price adjustments.
The ultimate impact will vary by sector, transaction size, merchant margins and payment volumes. The policy challenge will be to ensure that the new MDR supports a sustainable payments ecosystem without discouraging merchants from accepting UPI or undermining the convenience that has driven its widespread adoption.